Making Tax Digital · Sole traders
Groundworkers and MTD: excavator hire, CIS deductions, and drainage material costs
ONLY£15A MONTHUnderstand groundworks materials, plant hire with or without an operator, CIS tax deductions and quarterly Making Tax Digital records.
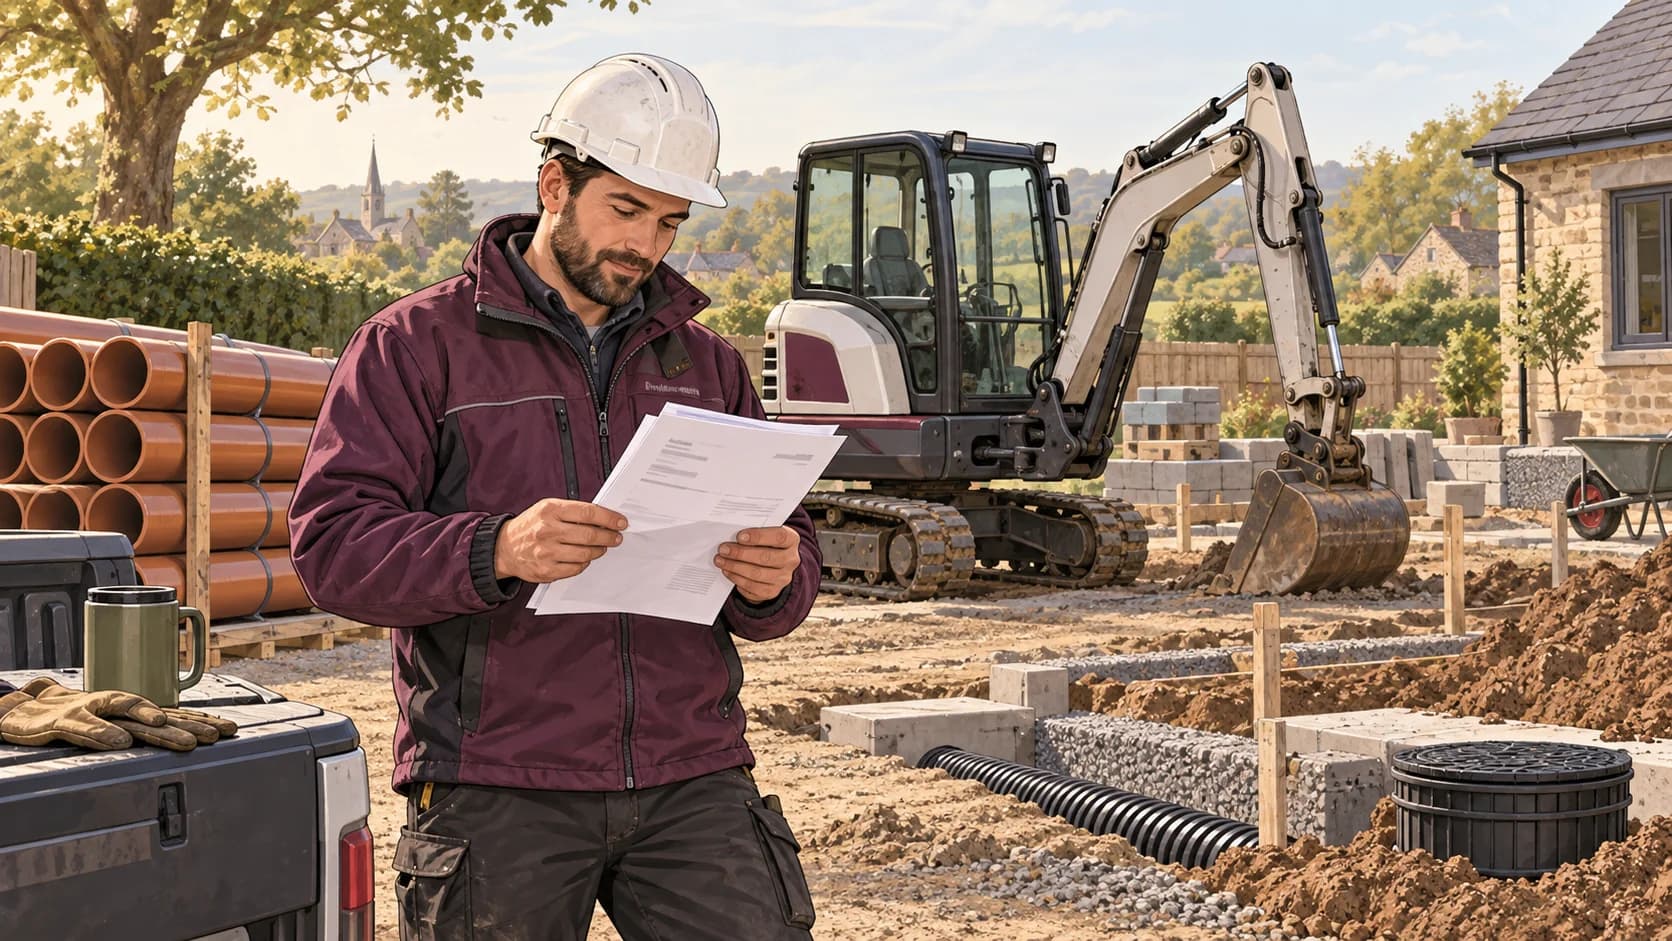
A groundworks payment can arrive after CIS tax has been withheld, while excavator hire and drainage materials are already paid. Looking only at the bank balance can leave both the job’s turnover and the tax already paid unclear.
Making Tax Digital is easier when those elements are recorded separately. You need the gross earnings, the allowable costs and the CIS deduction, supported by invoices and the contractor’s payment statement.
When Making Tax Digital applies
Making Tax Digital for Income Tax changes how qualifying sole traders and landlords keep records and report income. Under HMRC’s timetable, the starting points are:
- From 6 April 2026, if qualifying income exceeded £50,000 in 2024–25.
- From 6 April 2027, if qualifying income exceeded £30,000 in 2025–26.
- From 6 April 2028, if qualifying income exceeded £20,000 in 2026–27.
Qualifying income generally means gross self-employment and property income combined, before expenses. Salary, pension income and dividends do not count towards this particular test. Check HMRC’s qualifying income guidance, including the treatment of VAT and shorter accounting periods where relevant.
The test uses the relevant earlier tax year; passing a figure during a busy month does not mean you join that day. Exemptions can apply. These rules concern your individual business and property income, rather than a limited company’s Corporation Tax reporting.
Drainage materials and site supplies
Pipes, chambers, geotextiles, aggregate and other materials bought for customer work are normally business purchases. The amount charged for supplying them remains part of your income, including where supplied at cost. Record the purchase separately.
Keep merchant invoices, delivery charges and credits for unused materials. Under the cash basis, eligible costs generally follow payment timing; traditional accounting can require stock and work-in-progress adjustments.
Section 34 of the Income Tax (Trading and Other Income) Act 2005 supplies the business purpose test. Materials for private work at your own property need excluding, even if they share a delivery with a customer order.
Plant hire with and without an operator
Keep excavator, dumper, trench box and other hire agreements with the invoices. Identify delivery, damage charges, fuel and refundable deposits separately. A returned deposit is different from a refund of a hire expense.
There is also a CIS distinction. HMRC’s CIS 340 guide includes plant hire with an operator for use on site among construction operations. Hire of equipment without an operator is generally excluded as a standalone activity. Mixed contracts still require assessment as a whole.
That means paying for an operated excavator can raise subcontractor obligations that ordinary machine rental does not. Check the supplier’s actual service, employment status where relevant and your contractor responsibilities before treating every hire payment identically.
Owned equipment and running costs
Laser levels, pumps, fuel bowsers and suitable tools can qualify for relief. Most eligible equipment is deducted when paid for under the cash basis. Traditional accounting normally uses capital allowances, potentially the annual investment allowance, instead of deducting depreciation.
Finance needs the agreement rather than a guess from the monthly debit. An ordinary loan capital repayment is not another expense in addition to the plant purchase. Keep interest or rental charges separately identifiable according to the actual arrangement.
Fuel for business plant, servicing, repairs and suitable protective equipment can also be allowable. Retain receipts showing the use and exclude private spending. The tax treatment of fuel does not determine whether a particular fuel type is legally permitted in the machine or operation; check that question separately where relevant.
Worked example: keeping CIS tax separate
Ash invoices a contractor £8,000 for labour and £4,000 for materials directly bought at that cost. Assume a verified 20% CIS deduction rate, accepted material evidence and no VAT in this illustration.
| Item | Amount |
|---|---|
| Gross earnings | £12,000 |
| Direct materials excluded from deduction base | £4,000 |
| CIS deduction: 20% of £8,000 | £1,600 |
| Amount paid to Ash | £10,400 |
Ash records £12,000 gross income, the actual material expense and £1,600 CIS tax deducted separately. The deduction is not a business cost and does not reduce the gross income used for MTD.
The contractor must follow HMRC’s deduction calculation rules, including the correct rate and eligible exclusions. This simplified example does not cover every possible charge within a groundworks contract.
The deduction is a credit towards the annual bill
Keep the payment and deduction statement and reconcile it to the bank receipt. HMRC’s subcontractor tax guidance explains how deductions are considered in the annual tax position.
CIS withholding does not mean the job has been taxed twice or that a refund is guaranteed. The final result depends on annual profit, other income and the tax already paid. Check any pre-filled amounts against your statements.
Contractor duties and site records
If you pay subcontractors for construction work, monthly CIS reporting may apply alongside your own quarterly MTD updates. Returns are generally due by the 19th following the relevant tax month; HMRC’s monthly return guidance explains the requirements.
For VAT-registered work, check the construction reverse charge where relevant. Keep waste charges, plant returns and final material credits linked to the job. A short review at site completion can resolve costs while the details are still familiar.
Avona AI can support categorisation, while your contracts and CIS statements supply information that a net bank payment cannot show on its own.
A manageable quarterly routine
For a business using standard tax-year periods, the 2026–27 quarterly update deadlines are 7 August 2026, 7 November 2026, 7 February 2027 and 7 May 2027. Updates are cumulative: each covers the tax year so far. Calendar update periods are also available, with the same deadlines.
Keep digital income and expense records, reconcile them regularly and send the required totals through compatible software. The Income Tax (Digital Obligations) Regulations 2026 underpin the requirements; HMRC’s digital record-keeping notice explains the applicable directions. A bank feed needs supporting detail wherever a payment conceals fees, private purchases or several transactions.
Normally, record the transaction date, amount and relevant category, retaining supporting invoices or receipts. HMRC’s digital records guidance explains permitted simplifications and digital links where more than one software product is used.
Quarterly updates do not replace the annual tax return. The 2026–27 return is due by 31 January 2028, and normal tax payment dates continue. HMRC is not applying late quarterly update penalties for 2026–27, but digital records and updates are still required. That first-year approach does not waive other filing or payment obligations.
Keep earnings, costs and tax clearly connected
Explore Avona.app at £15/month for self-service use. Avona Concierge, managed by chartered accountants, starts from £60/month for ongoing help with groundworks accounts and reporting.