
Making Tax Digital · Sole traders
Dog trainers and behaviourists: field hire, training equipment, and quarterly MTD
ONLY£15A MONTHUnderstand field hire, canine training equipment, memberships, client travel and advance class fees under Making Tax Digital for Income Tax.
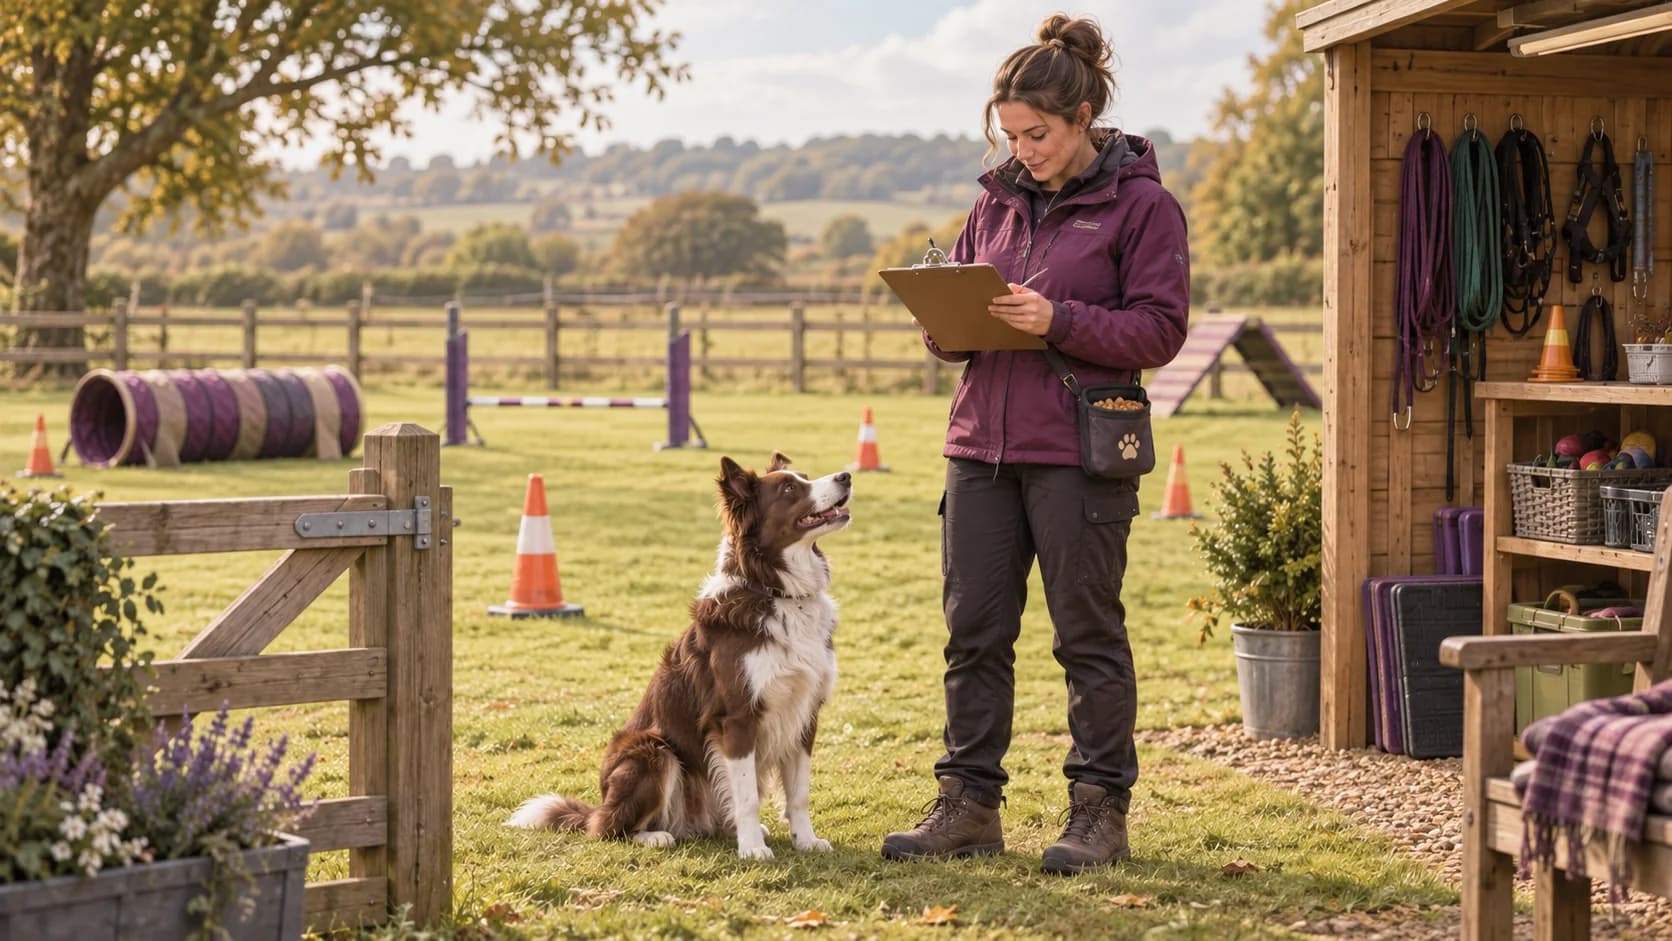
A puppy course may be paid for before it starts, while field hire and insurance continue regardless of how full the class is. Private behaviour consultations add another set of journeys, invoices and follow-up work.
For a sole trader dog trainer, useful tax records reflect how the business actually operates. Making Tax Digital adds a reporting timetable, but the essential decisions remain practical: which costs belong to the trade, when payments count and how to separate your own dog’s private expenses.
When Making Tax Digital applies
Making Tax Digital for Income Tax changes how qualifying sole traders and landlords keep records and report income. Under HMRC’s timetable, the starting points are:
- From 6 April 2026, if qualifying income exceeded £50,000 in 2024–25.
- From 6 April 2027, if qualifying income exceeded £30,000 in 2025–26.
- From 6 April 2028, if qualifying income exceeded £20,000 in 2026–27.
Qualifying income generally means gross self-employment and property income combined, before expenses. Salary, pension income and dividends do not count towards this particular test. Check HMRC’s qualifying income guidance, including the treatment of VAT and shorter accounting periods where relevant.
The test uses the relevant earlier tax year; passing a figure during a busy month does not mean you join that day. Exemptions can apply. These rules concern your individual business and property income, rather than a limited company’s Corporation Tax reporting.
Field and hall hire
The cost of renting a secure paddock or community hall for business classes can be allowable. Retain the hire invoice and booking details, including any refunds for cancelled sessions. A refundable security deposit needs separate treatment from the hire fee itself.
Check what the price includes. If the venue supplies equipment or utilities within a single hire charge, there is no additional expense merely because you can estimate their value. Your claim follows the amount actually incurred under the arrangement.
Section 34 of the Income Tax (Trading and Other Income) Act 2005 provides the business purpose test. HMRC’s guidance explains the need to exclude private expenditure, including private use of a field booked partly for your own leisure.
Training equipment and supplies
Long lines, treat pouches, scent-work supplies, suitable harnesses and teaching aids can be straightforward business purchases where used in the trade. Agility tunnels and weave equipment may also qualify, but retain invoices and note mixed use.
Under the cash basis, most eligible equipment is deducted when paid for. Traditional accounting can require capital allowances for lasting equipment. Do not substitute an estimated depreciation charge for the correct tax treatment.
| Purchase | What to establish |
|---|---|
| Long lines lent during paid classes | Business use and purchase cost |
| Scent supplies for a paid workshop | Link to the workshop and any private use |
| Agility equipment retained by the business | Ownership, payment method and business use |
| Food for your own household dog | Whether there is any separately identifiable business expense |
Your own dog appearing in demonstrations does not automatically make all its food, veterinary care and ordinary upkeep deductible. The personal purpose can remain substantial or inseparable. Document any specific business expenditure and seek advice before claiming general ownership costs.
Professional fees, insurance and development
Relevant APDT or IMDT membership, professional indemnity and public liability insurance may support your existing training business. Describe them according to their actual role rather than presenting voluntary memberships as a universal statutory licence.
HMRC’s subscriptions guidance and business insurance guidance explain the general treatment. Keep renewal invoices and check for duplicate cover or fees included within another package.
Behaviourist CPD and related training can qualify where they maintain or develop the existing trade. HMRC’s training rules distinguish that from expenditure preparing for an unrelated new business. Retain course descriptions where the connection is not obvious.
Client visits and class travel
Keep a journey log for home consultations, qualifying venue trips and equipment collection. Travel between clients normally has a clear business purpose. Travel from home to a regular separate workplace needs assessing on the working pattern; self-employment alone does not make it deductible.
For an eligible vehicle, simplified mileage is 55p for the first 10,000 business miles in 2026–27 and 25p thereafter. Alternatively, eligible actual costs may be used with the correct private-use adjustment. Previous claims restrict the choice, and the same running costs cannot be claimed through both methods.
Worked example: advance puppy-class bookings
Owen uses the cash basis and is not VAT registered. Eight clients each pay £150 in September for an October course. He pays £300 field hire and £80 for training supplies in September.
- Income received is 8 × £150 = £1,200.
- Costs paid total £380.
- The result before other costs is £820.
The ordinary course fees are recorded when received under the cash basis. They do not wait until the final class. Owen separately maintains a booking list showing the sessions still owed and any refund commitments.
If a client later receives a refund, record it with the original booking reference. If the payment provider deducts fees before settlement, reconcile the gross client payments, fees and net bank amount rather than treating the settlement as the whole sale.
A manageable quarterly routine
For a business using standard tax-year periods, the 2026–27 quarterly update deadlines are 7 August 2026, 7 November 2026, 7 February 2027 and 7 May 2027. Updates are cumulative: each covers the tax year so far. Calendar update periods are also available, with the same deadlines.
Keep digital income and expense records, reconcile them regularly and send the required totals through compatible software. The Income Tax (Digital Obligations) Regulations 2026 underpin the requirements; HMRC’s digital record-keeping notice explains the applicable directions. A bank feed needs supporting detail wherever a payment conceals fees, private purchases or several transactions.
Normally, record the transaction date, amount and relevant category, retaining supporting invoices or receipts. HMRC’s digital records guidance explains permitted simplifications and digital links where more than one software product is used.
Quarterly updates do not replace the annual tax return. The 2026–27 return is due by 31 January 2028, and normal tax payment dates continue. HMRC is not applying late quarterly update penalties for 2026–27, but digital records and updates are still required. That first-year approach does not waive other filing or payment obligations.
Keep the financial routine as clear as the class plan
Regular reviews of bookings, field charges and business purchases make quarter-end records easier to complete. Avona.app costs £15/month, with Avona AI supporting categorisation. Avona Concierge, managed by chartered accountants, starts from £60/month for ongoing human support.